Whether you’re thinking about buying your first home or trying to understand a mortgage you already have, the language of home loans can feel unfamiliar. What are you borrowing? How does repayment work? And what does that monthly payment actually cover?
You don’t need to learn every lending term at once. Home loan basics start with how a mortgage works, the main loan choices, and one useful distinction: your projected or current mortgage payment is not necessarily your full housing budget.
This guide connects those pieces so you can understand the commitment, plan for the costs, and ask useful questions—even if you haven’t started shopping for a loan yet.
How a Mortgage Works
A mortgage lets you borrow to buy a home and repay the money plus interest over an agreed period. The home secures the loan: nonpayment can lead to foreclosure, although the process and protections vary.
Your down payment is the money you put toward the purchase upfront. Your loan amount is what you borrow. Closing costs are separate upfront expenses for obtaining the loan and completing the purchase. They can include lender charges, appraisal and title-related costs, government fees, and prepaid expenses such as interest or insurance. The amount depends on the loan and transaction; saving a down payment doesn’t cover everything you may need at closing.
Principal is the borrowed money you must repay. Interest is the cost of borrowing it. With most home loans, regular payments gradually reduce the principal balance. This process is called amortization. With a typical fixed-rate, fully amortizing loan, the interest portion starts higher and shrinks over time as more of the scheduled principal-and-interest payment goes toward the balance. Some loans use different structures, so check yours.
Equity is your home’s current value minus what you owe on mortgages against it. Paying down principal can build equity, but changes in the home’s value matter too. A home-equity loan generally provides a lump sum; a home equity line of credit (HELOC) lets eligible owners draw from an available credit limit. Both use the home as security and create debt to repay, with possible fees and costs. Equity is not free cash; failing to repay can put the home at risk.
The Main Loan Choices
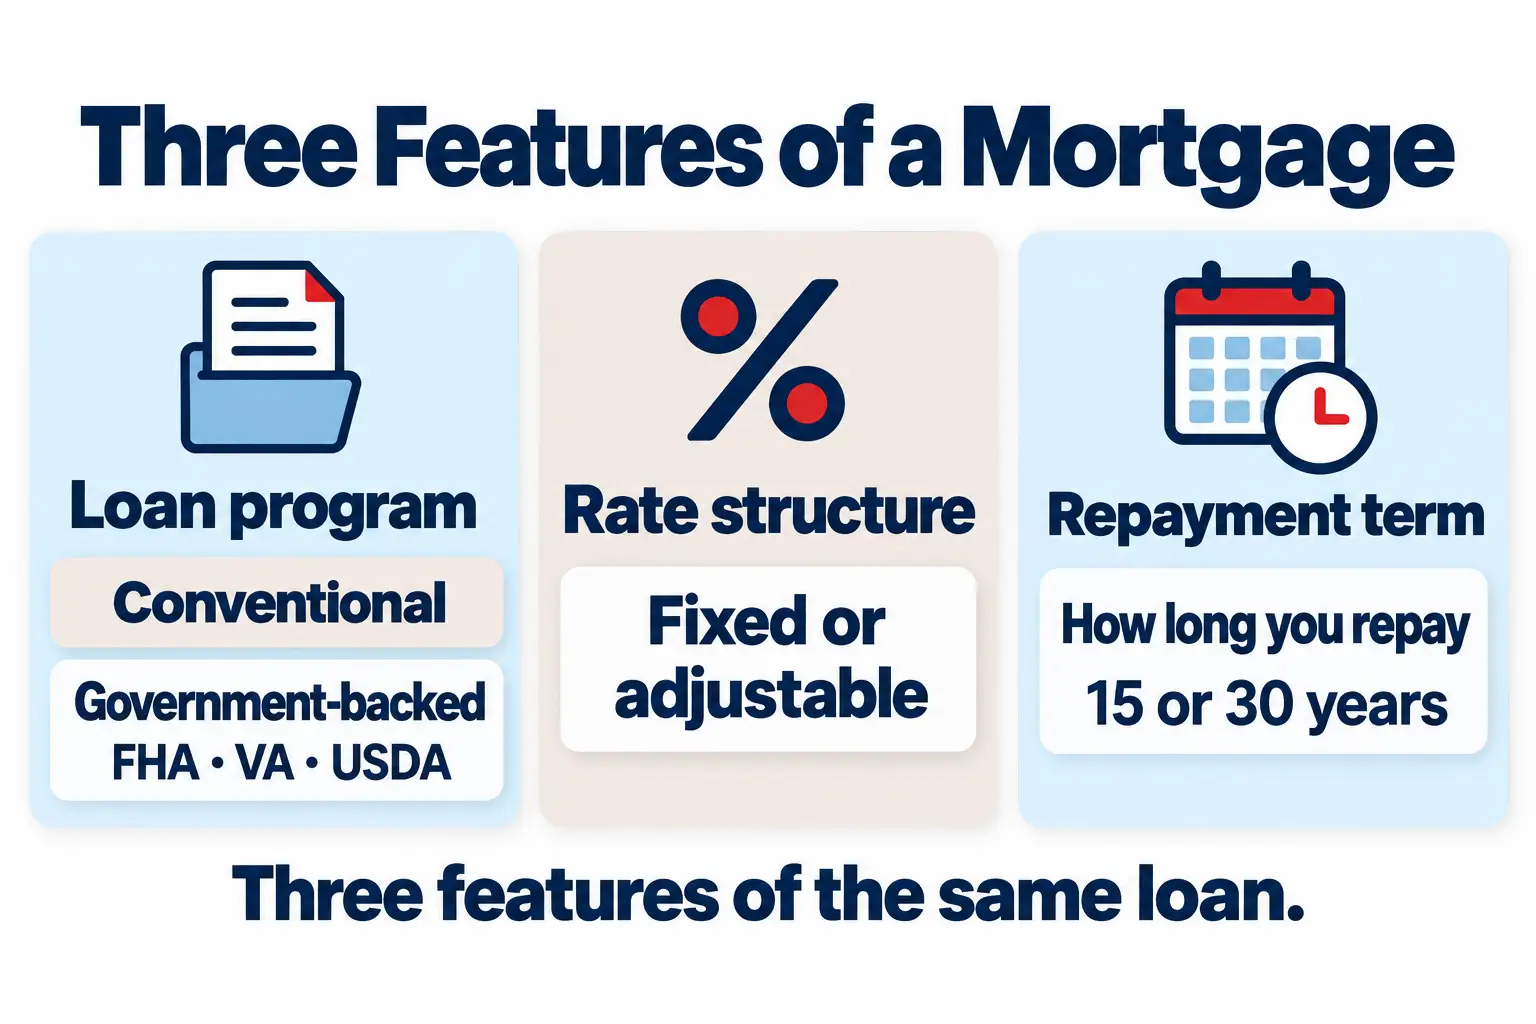
Loan names describe different parts of the same mortgage. Start with the program, the interest-rate structure, and the repayment term.
A conventional loan isn’t insured or guaranteed through a government mortgage program. Government-backed loans include Federal Housing Administration (FHA), Department of Veterans Affairs (VA), and U.S. Department of Agriculture (USDA) programs. Their eligibility, down-payment and other requirements differ; a program name alone doesn’t tell you whether you qualify or which offer fits best.
With a fixed-rate mortgage, the interest rate stays the same for the loan term. With an adjustable-rate mortgage (ARM), it can change under the loan’s terms, often after an initial fixed period. Program and rate structure are separate choices: “conventional” and “fixed-rate” describe different features.
The loan term is how long you have to repay, often 15 or 30 years. It affects the monthly principal-and-interest payment and the interest paid over time. We’ll return to that tradeoff when comparing offers.
You don’t need to choose a loan from these labels alone. First understand what each feature means; then look at the payment and costs together.
What Lenders Consider
A lender evaluates your application and makes the loan. Lenders generally review income and employment, existing debts, credit history and scores, and available cash or other assets. The loan program also affects the requirements.
Your debt-to-income ratio (DTI) compares monthly debt payments with gross monthly income—income before taxes and deductions. It is one way lenders assess repayment capacity; limits vary by lender and loan product.
Qualifying and feeling comfortable with the cost are different questions. A lender’s approval doesn’t account for every household priority. Keep your spending, savings and future needs in the decision.
Home Loan Basics: What Your Payment Includes
Your payment can combine several costs. A servicer collects payments and handles ongoing loan administration, including escrow when applicable. The lender and servicer may be the same company or different companies. Knowing the difference helps you direct questions to the right place.
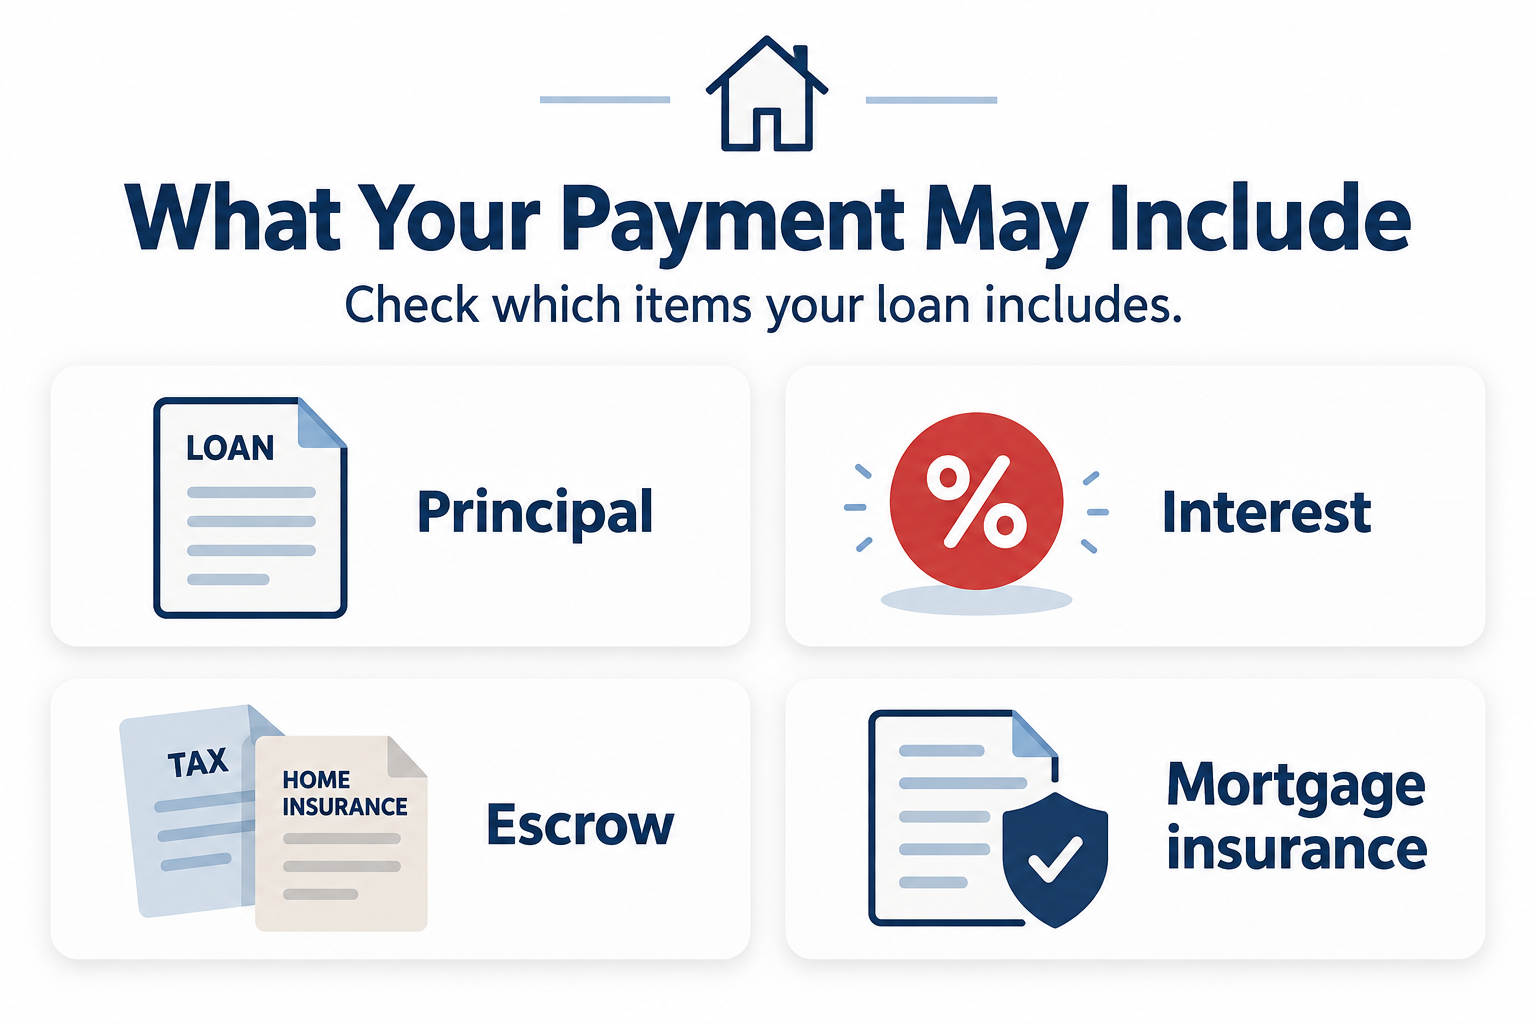
Principal and interest make up the loan-repayment portion of your payment. Escrow and mortgage insurance, when applicable, are additional components to check.
Mortgage escrow is money collected with your payment for certain bills, such as property taxes and homeowners insurance. The servicer pays the covered bills from that account. Some loans have no escrow, and not every housing cost belongs in it.
Mortgage insurance may be part of the payment, depending on your loan. It generally protects the lender if you stop paying, rather than insuring your home or belongings. Keep it separate from homeowners insurance.
The Consumer Financial Protection Bureau (CFPB) explains the difference between principal and interest and your total mortgage payment. The practical question is simple: “Which costs are included in this figure, and which will I pay separately?”
Two Totals That Keep the Costs Clear
It helps to write down two numbers: what goes to your servicer and what you plan to spend or set aside for housing overall.
The table below shows an example with escrow. All figures are illustrative—not a loan quote or an affordability target. Your costs will depend on your loan, property, location, and household.
| Payment or Budget Item | Hypothetical Monthly Amount | How It’s Handled |
|---|---|---|
| Principal and interest | $1,500 | Included in the servicer payment |
| Escrow for property taxes and homeowners insurance | $450 | Included in the servicer payment |
| Mortgage insurance | $100 | Included in the servicer payment |
| Monthly payment to your mortgage servicer | $2,050 | The amount sent to the servicer |
| Association dues | $150 | Budgeted separately |
| Utilities | $300 | Budgeted separately |
| Maintenance and repair reserve | $200 | Planned saving for future needs |
| Separately budgeted costs and reserve | $650 | Association dues, utilities, and planned saving for repairs |
| Total monthly household housing budget | $2,700 | Servicer payment plus the selected separate costs and reserve |
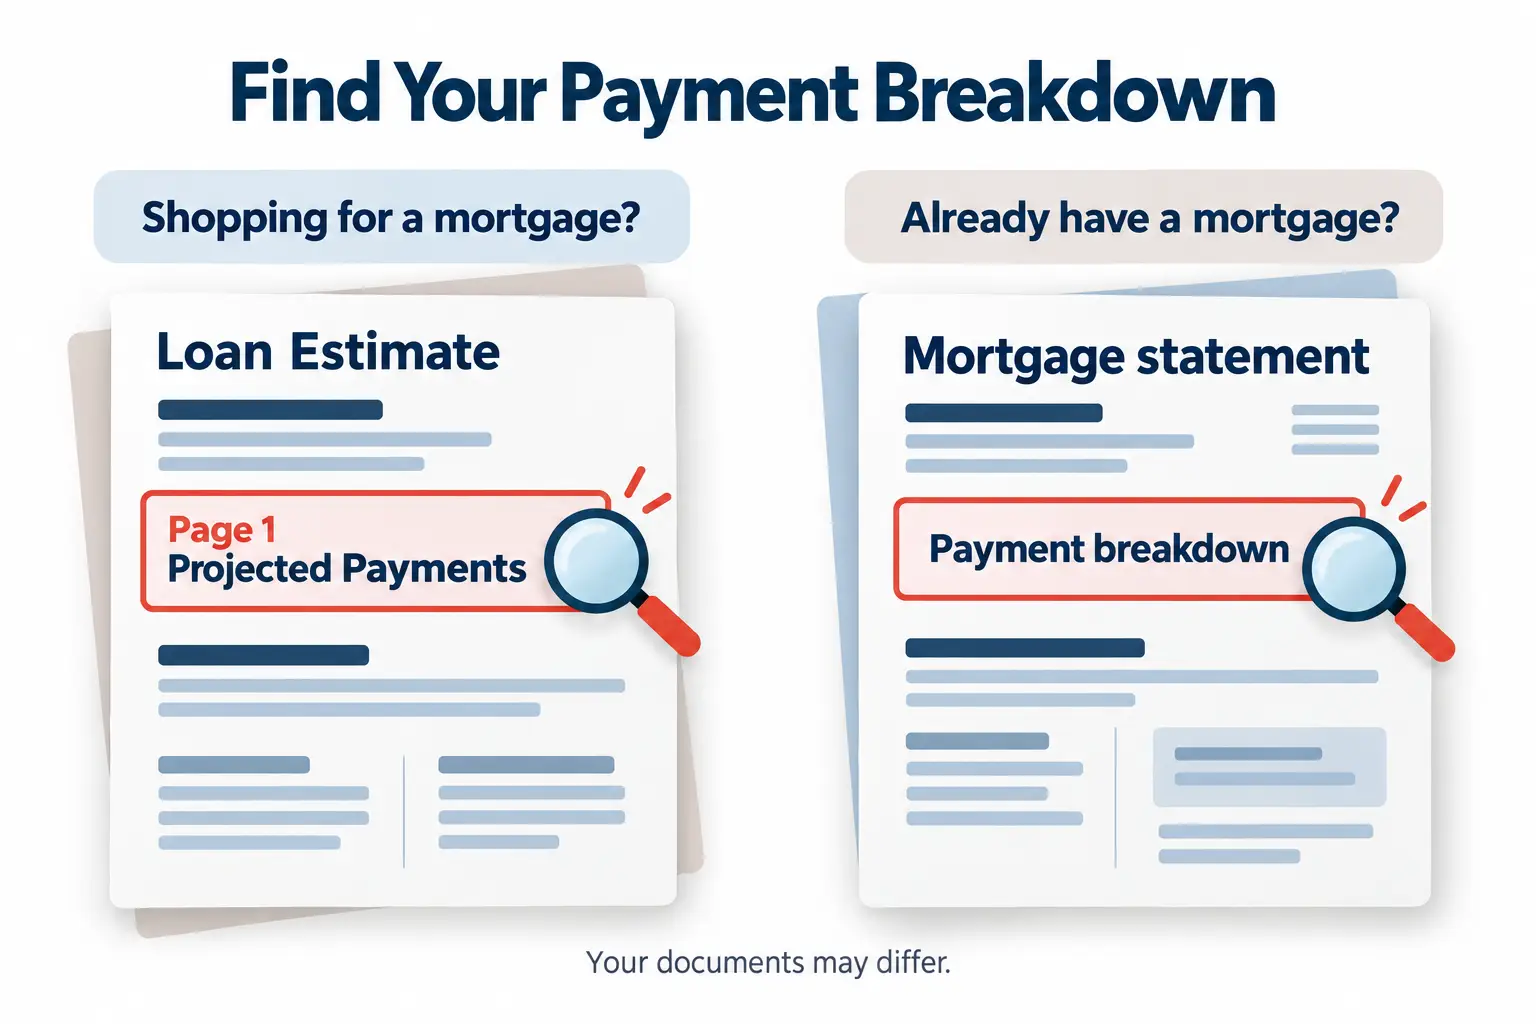
Find your loan figures in Projected Payments on page 1 of a Loan Estimate or your mortgage statement’s payment breakdown. Ask about unclear charges. Use association statements and utility bills for separate costs, and choose a repair reserve that reflects your home’s needs.
The repair reserve is planned saving, not a bill due that month. The example doesn’t cover every possible expense beyond the mortgage payment.
What if the same hypothetical loan had no escrow? Keeping all other assumptions unchanged, you would send $1,600 to the servicer for principal, interest, and mortgage insurance. You would budget the $450 for taxes and homeowners insurance separately, leaving the same $2,700 total monthly household housing budget.
That $450 is a monthly budgeting amount, not a claim that tax and insurance bills arrive monthly. Without escrow, the bills still count—you’re simply handling them outside the mortgage payment.
Fit the Full Housing Budget Into Your Life
Once you have the broader housing total, you can see how a home would fit alongside the rest of your life. Compare it with your everyday spending, savings and other priorities—not just the amount a lender will approve.
Start with the bills you know about and leave room for maintenance and repairs. You don’t need to predict everything to make a useful plan. AHA’s guide to planning first-year bills and maintenance can help you plan for those needs.
As you build that plan, don’t count an expense twice. Taxes and homeowners insurance collected through escrow are already in the mortgage payment. If they aren’t escrowed, give them a place in your separate budget.
The CFPB’s guidance on deciding how much you want to spend includes taxes, insurance, association fees where applicable, utilities, maintenance, and repairs. There isn’t one universal allowance that fits every home.
You’ll also need to plan for cash needed at closing. Keep that upfront requirement separate from the monthly budget so you can see both what it takes to buy and what it takes to live there.
What Can Change After You Close?
With a typical fixed-rate mortgage, the scheduled principal-and-interest payment stays the same. The total amount sent to the servicer can still change because of escrow, mortgage insurance, or other applicable charges.
For example, property taxes or homeowners insurance costs can change, affecting the escrow portion even when your interest rate hasn’t moved. An escrow shortage can also raise your monthly payment if your servicer collects repayment through it.
One Escrow-Change Example
Using the same hypothetical figures, suppose monthly escrow increases from $450 to $500. Principal and interest stay at $1,500, and mortgage insurance stays at $100.
Your servicer payment rises from $2,050 to $2,100. With all other illustrated budget items unchanged, your total monthly household housing budget rises from $2,700 to $2,750.
That’s a $50 change in both totals. It demonstrates one possible escrow-related increase—not a prediction or an explanation of every escrow shortage or payment change. If your payment has actually increased, AHA’s guide to understanding a mortgage payment increase walks through the documents and questions to review.
If you have or are considering an adjustable-rate mortgage, also check when its rate may adjust and how that could affect the payment.
Private mortgage insurance (PMI) cancellation on a conventional loan has requirements and conditions. Other programs and lender-paid insurance differ. Gaining equity doesn’t automatically end every charge; check your loan’s rules.
If you’re considering refinancing your mortgage, compare the new loan’s upfront and ongoing costs. Refinancing replaces your existing mortgage; availability, better terms and savings aren’t guaranteed.
Where to Look on Your Loan Paperwork
The terms you’ve learned become more useful when you can find them in your own paperwork. Start with the document that fits where you are in the process.
If You’re Shopping for a Mortgage
For a loan that uses a Loan Estimate, start with Loan Terms on page 1. This section shows the loan amount, interest rate, monthly principal-and-interest payment, and whether there is a prepayment penalty or balloon payment. Check the loan type and term near the top of the page, too.
Then look at Projected Payments for the estimated total monthly payment and what could change. Review estimated taxes, insurance and assessments, including which costs aren’t escrowed.
Turn to the cash-to-close details on page 2 to see the estimated upfront requirement. That figure answers a different question from your monthly payment.
The CFPB’s Loan Estimate explainer can help you locate these figures. For the broader buying process, see AHA’s first-time homebuyer guide.
If You Already Have a Mortgage
Your mortgage statement is a useful starting point for the amount due, principal, interest, escrow, fees and rate. Some borrowers receive coupon books, and statement requirements have exceptions, so use the documents and notices supplied for your loan.
If the escrow amount changed, the statement alone may not explain why: its escrow line may not itemize the underlying bills. Review the escrow notice and bills, or ask your servicer which part changed and what accounts for the difference.
Compare the Commitment, Not Just the Payment
Compare loan amount, rate, payment components and upfront costs together. A lower displayed payment doesn’t establish a better loan.
When comparing repayment terms, weigh the monthly payment against interest paid over time. For otherwise comparable loans, a longer term generally lowers the principal-and-interest payment but can mean more total interest. Request estimates for the same loan type and term whenever possible.
Watch Out: Incomplete Payment Comparisons One figure may include escrow and mortgage insurance while another shows only principal and interest. Even when both include escrow, different tax or insurance estimates can make one appear cheaper. Confirm what each figure includes before comparing them.
The CFPB’s guide to comparing loan offers supports comparing like with like. Ask the lender to explain differences.
Two terms help you examine the trade-off between upfront and ongoing borrowing costs:
Annual percentage rate (APR) expresses the annualized cost of borrowing, reflecting the interest rate and certain loan fees. It helps compare borrowing costs, but isn’t your household housing budget or an ARM’s maximum possible future rate.
Discount points generally exchange an upfront payment for a lower rate. Rate-linked lender credits generally exchange a higher rate for lower upfront costs. Neither is automatically better; review the tradeoff in your offer.
Also check unusual repayment features: a balloon payment is a large lump sum, typically due at the end; a prepayment penalty is a fee for certain early repayments. If either appears, ask how it works and compare an offer without it.
One Useful Next Step
You can leave the rest of the mortgage vocabulary for later. Focus first on getting a complete payment picture.
- If buying is still a future plan: Start a housing budget that includes costs beyond the loan payment, and use the loan basics above to prepare your questions before speaking with lenders.
- If you’re shopping: Open your Loan Estimate and ask the lender to confirm what’s included in the projected payment and which housing costs you’ll pay separately.
- If you already have a mortgage: Open your latest statement or coupon book and relevant notices, then ask your servicer to clarify any payment component you can’t explain.
Understanding these pieces helps you plan without becoming a mortgage expert. For more plain-language help, explore homeowner guidance from AHA.